Guest post by: Eyal Harel, CEO, BlueGreen Water Technologies
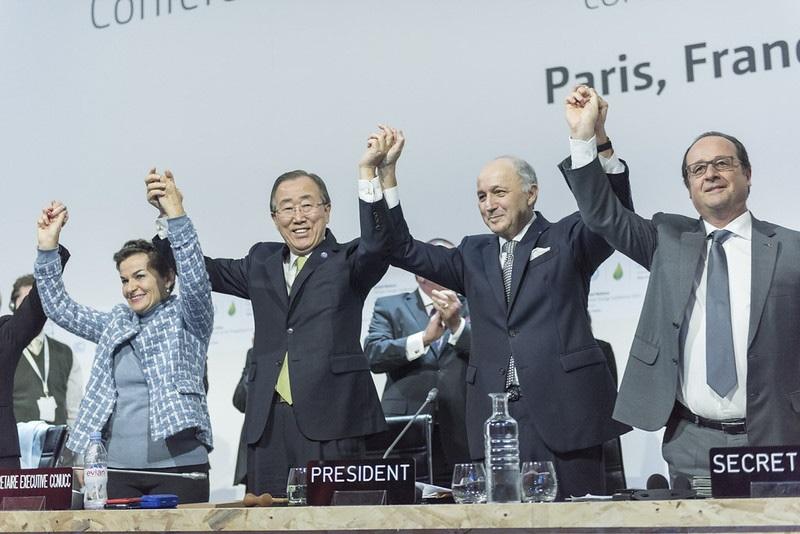
The Paris Agreement was conceived as a bold, ambitious framework to unite nations in a common effort against climate change. Article 6, which established mechanisms for international carbon trading, was meant to be the financial engine of that ambition – channeling private capital toward emissions reductions at scale. Instead, the rules that have emerged from years of painstaking negotiation, particularly the requirements for Corresponding Adjustments (CAs) and Letters of Authorization (LoAs), have created a regulatory labyrinth so impenetrable that they are actively suffocating the very markets they were designed to enable. The planet cannot afford this contradiction.
True, under normal circumstances, the urgency for immediate, scalable climate action was only heightened by the UNEP’s recent warning that the former maximal target of 1.5C degrees – is no longer attainable.
The logic behind corresponding adjustments is, in principle, coherent. When a country sells a carbon credit to an international buyer, it has agreed to reduce or remove a unit of greenhouse gas emissions on behalf of someone else. If that country then counts the same reduction toward its own Nationally Determined Contribution (NDC), it is effectively double counting the same ton of CO2. Corresponding adjustments were designed to prevent this; the selling country puts the credit back into its own inventory, and the buying country subtracts it. One action, one claim.
The Letter of Authorization requirement accompanies this logic by demanding that sovereign governments formally authorize each international transfer of carbon credits, providing a government guarantee that the credit will not be double counted in the national inventory. On paper, these are reasonable safeguards against fraud or abuse. In practice, they have become millstones around the neck of global climate finance.
The first and most fundamental problem with the CA-LoA framework is structural: it places the burden of sovereign compliance on private project developers. A solar developer in Kenya, a reforestation company in Colombia, or a biogas enterprise in Vietnam must now secure formal, binding government authorization before they can sell carbon credits internationally and must trust that the same (or future) government will honor its accounting commitments over the lifetime of a project that may span decades.
This is not a theoretical concern. Carbon projects routinely have 10, 20, or even 30-year lifespans. Over such time frames, governments change, policies reverse, and ministries are restructured. For example, in 2023, Zimbabwe sent shockwaves through the carbon markets by unilaterally declaring a 50% revenue tax on all carbon projects in the country, with little warning to the private developers who had invested on the assumption of stable terms. In countries where political risk is already elevated, which are precisely the countries that often host the most cost-effective mitigation opportunities, asking a private developer to stake their balance sheet on the long-term consistency of sovereign accounting is not just unreasonable; it is commercially impossible to underwrite.
No institutional investor, commercial bank or project finance structure in the world is built to absorb open-ended sovereign political risk without compensation. Yet the CA-LoA framework effectively demands exactly that, for free, as a precondition for market participation. The result is predictable: developers withdraw, investors retreat, and projects that could have absorbed or reduced millions of tons of CO2 never break ground.
The collapse of KOKO Networks in Kenya in January 2026, as discussed in part 1 of this two-part series, illustrates the consequences. Despite more than $300 million in investment and political risk insurance from the World Bank’s Multilateral Investment Guarantee Agency (MIGA), the company ceased operations after failing to secure the government authorization needed to sell its carbon credits internationally.
Letters of Authorization are not standardized across jurisdictions with authorization processes and requirements varying between countries. For developers seeking to plan and finance long-term projects, this creates additional regulatory uncertainty. Host countries retain broader strategic discretion to withhold or constrain authorization even where no formal suspension exists. As Sylvera has documented, a significant opportunity cost shapes host-country decision-making: every credit a government authorizes for international transfer must be put back on its own NDC ledger, leaving it with a narrower pool of domestic reductions to claim.
Countries with increasingly ambitious NDC targets, which must be increased every five years under the Paris Agreement, face a growing structural incentive to restrict authorizations rather than expand them, precisely as global demand for compliant credits is rising. The result is a market in which supply is systematically constrained by the very architecture that was supposed to unlock it.
For a developer trying to model cash flows over a 15-year project horizon, this is not a manageable variable. Credit rating agencies and project finance lenders, who are accustomed to modeling regulatory risk, are having difficulties advancing capital against Article 6-compliant credits because the compliance pathway cannot be modeled with sufficient confidence. The result is a systemic economic disincentive whereby projects that are climate-sound, financially viable on their operating merits, and urgently needed are simply not being executed because the regulatory framework governing their revenue stream is too unstable to finance.
Perhaps the most contradictory element of the current framework is the requirement that corresponding adjustments apply even to credits generated by private projects that received no government funding or involvement whatsoever. A private company that independently finances, develops, and operates a carbon removal facility must nonetheless adjust its verified reductions with the host country’s national carbon accounting — an adjustment the government did not invite and did not budget for when setting its NDC targets, further creating a potential disinterest from the host country in authorizing carbon projects to which it would otherwise be indifferent.
None of this is an argument against environmental integrity. Double counting is a real problem, and the international carbon market must have credible safeguards against it. However, there is a profound difference between safeguards that achieve their objective efficiently and requirements that impose enormous costs while providing only marginal additional integrity over what technology already delivers.
Policymakers should urgently pursue four reforms. First, they should embrace ledger-based integrity assurance as the primary anti-double-counting mechanism, reducing the burden on sovereign authorization as a precondition for issuance. If the ledger shows a credit exists and has not been retired, it exists. If a government wants to claim it, the ledger will show that claim, and any competing claim will be immediately visible. Second, corresponding adjustment obligations should apply only to credits that host governments have affirmatively chosen to authorize for international transfer, not to all privately developed credits as a default. Third, the LoA process should be standardized, time-bound, and subject to clear appeal mechanisms, so that developers can build regulatory timelines into their project plans with reasonable confidence. Fourth, a de minimis threshold should exempt small-scale and community-based projects from the full CA-LoA regime entirely, preserving their access to international finance without the overhead that their economics cannot support.
The Paris Agreement was not written to produce paperwork. It was written to save the planet. The corresponding adjustment framework, as currently implemented, produces a great deal of the former and very little of the latter. That is a policy failure, and unlike the climate crisis itself, it’s one we have the tools and the authority to fix immediately.
Photo: UN Photo/Mark Garten